Where’s your next home?
Blending digital innovation with real estate precision to secure your real estate needs.
What It Actually Costs to Buy in the GTA
Beyond the purchase price, two numbers decide whether a home is really affordable for you: your down payment and your closing costs. Here is the straight answer on both, plus how first-time buyer programs stack together.
How Much Down Payment Do You Need?
The minimum down payment in Canada is set federally and scales with the purchase price:
- Up to $500,000 — minimum 5% down
- $500,000 to $999,999 — 5% on the first $500,000, plus 10% on the portion above that
- $1,000,000 and up — minimum 20% down, and you will need a conventional (uninsured) mortgage rather than an insured one
Example: on a $650,000 condo, that is 5% of $500,000 ($25,000) plus 10% of the remaining $150,000 ($15,000), for a minimum down payment of $40,000.
What Closing Costs Should You Budget For?
Plan for these on top of your down payment:
- Ontario Land Transfer Tax — payable on every purchase in Ontario. First-time buyers can claim a refund of up to $4,000, which covers the tax in full on homes up to roughly $368,000 and reduces it on anything above that.
- Toronto Municipal Land Transfer Tax — if you are buying within the City of Toronto specifically, there is a second, municipal land transfer tax on top of the Ontario one, with its own separate first-time buyer rebate. Richmond Hill, Markham, Vaughan and the rest of York Region do not have this second tax.
- Legal fees — typically $1,500–$2,500 for a residential purchase
- Title insurance — usually arranged by your lawyer, a few hundred dollars
- Home inspection — commonly $400–$700
- Adjustments — reimbursing the seller for prepaid property tax or utilities from your closing date forward
A common rule of thumb is to budget 1.5%–4% of the purchase price for closing costs, on top of your down payment.
First-Time Buyer Programs, and How They Stack
These are not mutually exclusive — most first-time buyers use several of these together:
- Ontario Land Transfer Tax Refund — up to $4,000 back, applied automatically at closing by your lawyer if you qualify.
- RRSP Home Buyers' Plan (HBP) — withdraw up to $60,000 from your RRSP, tax-free, toward your down payment. You repay it back into your RRSP over 15 years.
- First Home Savings Account (FHSA) — contribute up to $8,000 per year ($40,000 lifetime max). Contributions are tax-deductible going in, and withdrawals are completely tax-free when used for a qualifying first home purchase.
- First-Time Home Buyers' Tax Credit — a $10,000 non-refundable federal tax credit, worth up to roughly $1,500 back at tax time.
A typical stack looks like this: use your FHSA and RRSP HBP together to boost your down payment, claim the Ontario refund at closing, and claim the tax credit the following spring. Program rules and dollar limits do change with federal and provincial budgets, so confirm current numbers with your mortgage professional before you build your budget around them.
Buyer's Handbook: Frequently Asked Questions
What is the minimum down payment for a condo or home in the GTA?
5% on the portion of the price up to $500,000, 10% on the portion between $500,000 and $999,999, and 20% minimum on $1,000,000 and up. A $650,000 condo needs a minimum down payment of $40,000.
What closing costs should I budget for beyond the purchase price?
Ontario land transfer tax (with up to a $4,000 first-time buyer refund), legal fees, title insurance, a home inspection, and adjustments for prepaid property tax or utilities. Budget roughly 1.5% to 4% of the purchase price.
Can I use the RRSP Home Buyers' Plan and the FHSA together?
Yes. The RRSP Home Buyers' Plan (up to $60,000) and the First Home Savings Account (up to $40,000 lifetime) can both be used toward the same first home purchase, on top of the Ontario land transfer tax refund.
Do I have to pay back the First-Time Home Buyers' Tax Credit?
No. It is a one-time, non-refundable tax credit on $10,000 of eligible costs, worth roughly $1,500 back on your tax return. Unlike the RRSP Home Buyers' Plan, there is nothing to repay.
What first-time buyer programs stack together in Ontario?
Most first-time buyers combine the RRSP Home Buyers' Plan, the FHSA, the Ontario land transfer tax refund, and the First-Time Home Buyers' Tax Credit. None of these programs disqualify you from the others.
Real Estate Tools and Resources

MORE LISTINGS
Browse active homes and condos across the GTA, from first homes to investment properties, synced directly from the MLS® and updated hourly.

WORK WITH A BROKER
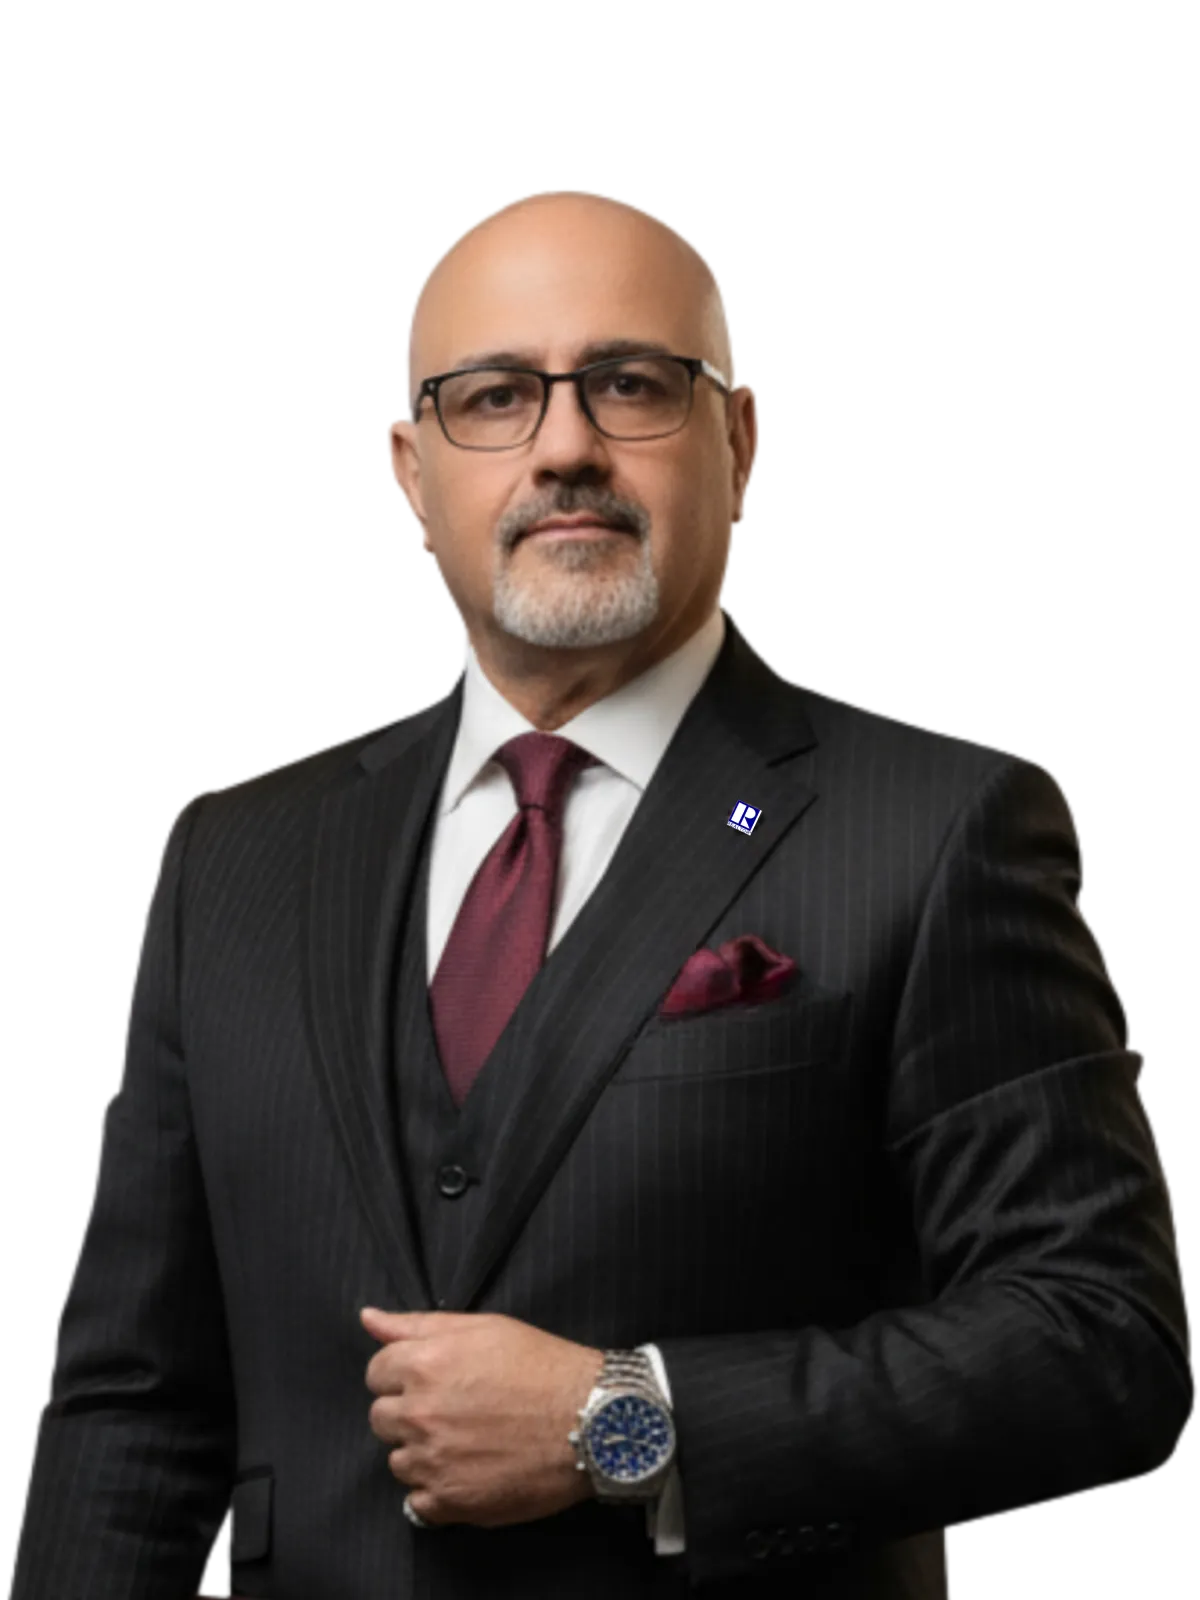
Ali Bolourchi, BSc, MS, PSA, ABR®, Broker of A.B.R.E. Team with REMAX® Your
Community Realty Inc. Not a call center, not a lead-form black hole.

HOME EVALUATIONS
Get a realistic read on what your home is worth in today's market before you list it, based on what has actually sold nearby.
Meet Your Broker
Ali Bolourchi
BSC, MS, PSA, ABR®, REALTOR® Broker
REMAX® Your Community Realty, Brokerage*
416-886-2000
Innovation
Fresh, creative solutions.
Integrity
Honesty and transparency.
Excellence
Top-notch services.
Proud Member of
TRREB (Toronto Regional Real Estate Board)
CREA (Canadian Real Estate Association)
OREA (Ontario Real Estate Association)
CCC (Canadian Commercial Council of REALTORS®)
CCIM (Certified Commercial Investment Member)
NAR (National Association of REALTORS®)
PSA (Certified Pricing Strategy Advisor)
ABR® (Accredited Buyer Representative)
AREAA (Asian Real Estate Association of America)
Office: 905-731-2000 | Mobile: 416-886-2000 | [email protected]
Office: 8854 Yonge Street, Richmond Hill, ON, L4C 0T4
FOLLOW US


Copyright 2026. ABRE Team. All Rights Reserved. Privacy Policy | Terms of Use
* Each Office Independently Owned and Operated.
This website may only be used by consumers that have a bona fide interest in the purchase, sale, or lease of real estate of the type being offered via the website.
The data relating to real estate on this website comes in part from the MLS® Reciprocity program of the PropTx MLS®. The data is deemed reliable but is not guaranteed to be accurate.